
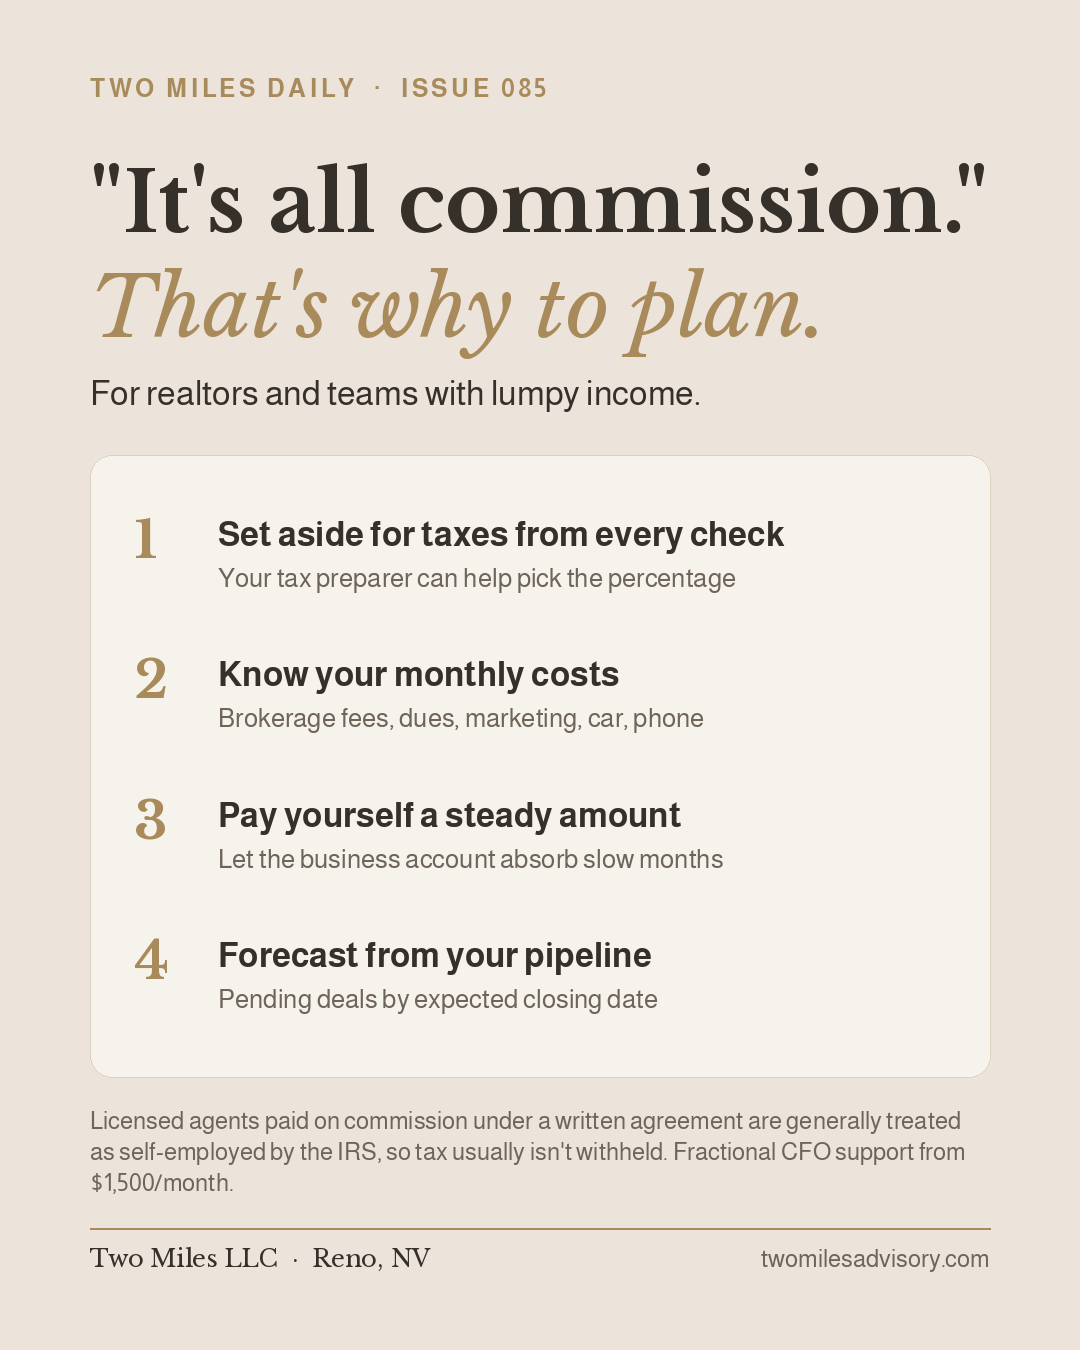
When I mention fractional CFO support to realtors, I sometimes hear, "My income is all commission. There's nothing to plan."
I'd argue the opposite. Lumpy income is exactly why a plan helps.
No one is withholding for you. If you're a licensed agent paid on commission under a written agreement, the IRS generally treats you as self-employed. That usually means no tax is withheld from your checks, and individuals generally have to make estimated tax payments if they expect to owe $1,000 or more when they file. A set percentage from every closing, moved to a separate account the day it lands, keeps tax time from being a surprise. Your tax preparer can help you pick the percentage.
What a plan looks like for an agent or a team:
• Know your monthly costs. Brokerage fees, dues, marketing, your car, your phone, any assistant. That's the number your closings have to cover before you get paid.
• Pay yourself steady. Commissions go into the business account. You pay yourself a set amount each month, and the account absorbs the slow months.
• Forecast from your pipeline. List pending deals by expected closing date, and count only what's likely to close. That shows the next few months more clearly than last month's bank balance.
• Track what your marketing produces. Which lead sources actually turned into closings, and what each one cost.
• Plan team decisions with numbers. Before you add an agent, an assistant or a new split, see what it does to your cash.
For a busy agent or a growing team, this turns "I hope it's a good year" into a plan you can act on.
— Rachel, Two Miles LLC